

Earnings results often indicate what direction a company will take in the months ahead. With Q2 behind us, let’s have a look at Lam Research (NASDAQ:LRCX) and its peers.
The semiconductor industry is driven by demand for advanced electronic products like smartphones, PCs, servers, and data storage. The need for technologies like artificial intelligence, 5G networks, and smart cars is also creating the next wave of growth for the industry. Keeping up with this dynamism requires new tools that can design, fabricate, and test chips at ever smaller sizes and more complex architectures, creating a dire need for semiconductor capital manufacturing equipment.
The 14 semiconductor manufacturing stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 3.5% while next quarter’s revenue guidance was 6.5% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 7.5% since the latest earnings results.
Lam Research (NASDAQ:LRCX)
Founded in 1980 by David Lam, the man who pioneered semiconductor etching technology, Lam Research (NASDAQ:LRCX) is one of the leading providers of wafer fabrication equipment used to make semiconductors.
Lam Research reported revenues of $6.72 billion, up 30% year on year. This print was in line with analysts’ expectations, and overall, it was an exceptional quarter for the company with a beat of analysts’ EPS estimates and revenue guidance for next quarter exceeding analysts’ expectations.
"Lam delivered record revenue, operating margin and earnings per share in the June quarter as AI-driven demand continues to reshape the semiconductor industry," said Tim Archer, Lam Research's President and Chief Executive Officer.
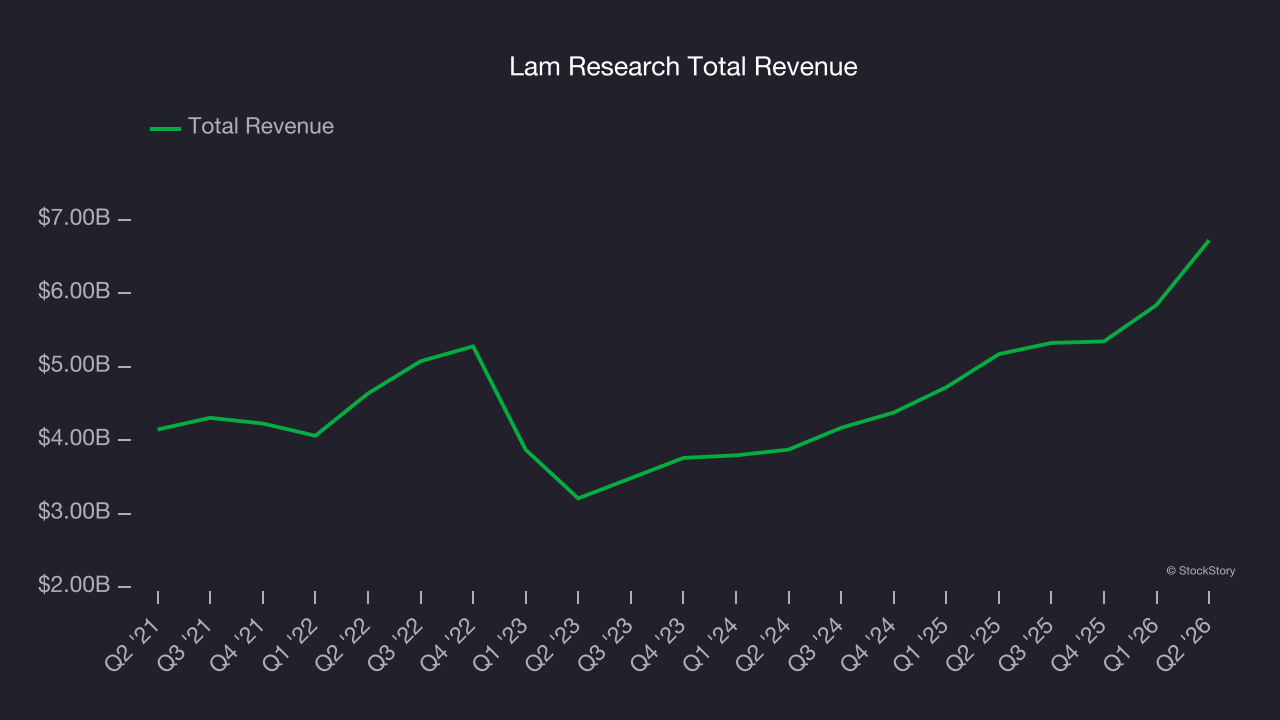
Interestingly, the stock is up 4.9% since reporting and currently trades at $264.60.
Best Q2: Kulicke and Soffa (NASDAQ:KLIC)
Headquartered in Singapore, Kulicke & Soffa (NASDAQ: KLIC) is a provider of production equipment and tools used to assemble semiconductor devices
Kulicke and Soffa reported revenues of $330.4 million, up 123% year on year, outperforming analysts’ expectations by 5.7%. The business had a stunning quarter with a significant improvement in its inventory levels and a beat of analysts’ EPS estimates.
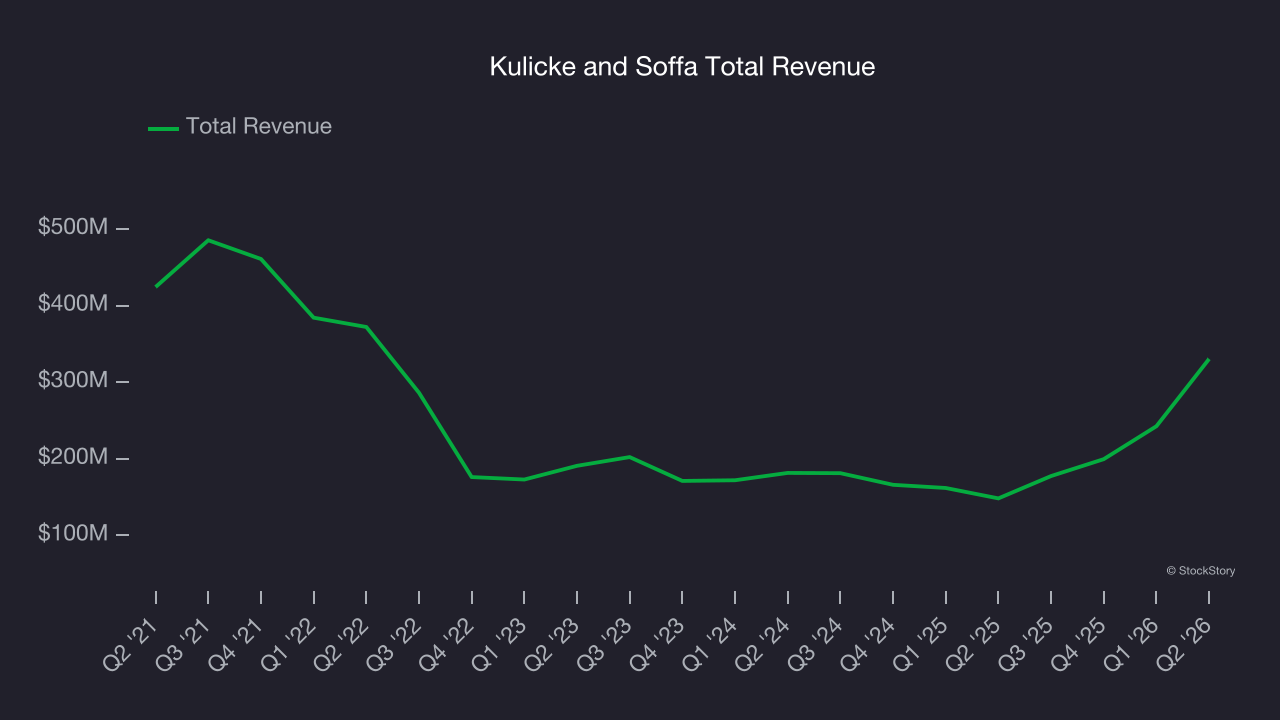
Kulicke and Soffa pulled off the fastest revenue growth of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 16.4% since reporting. It currently trades at $78.50.
Is now the time to buy Kulicke and Soffa? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: KLA Corporation (NASDAQ:KLAC)
Formed by the 1997 merger of the two leading semiconductor yield management companies, KLA Corporation (NASDAQ:KLAC) is the leading supplier of equipment used to measure and inspect semiconductor chips.
KLA Corporation reported revenues of $3.66 billion, up 15.2% year on year, exceeding analysts’ expectations by 1.3%. It may have had the worst quarter among its peers, but its results were still good as it also locked in a beat of analysts’ EPS estimates and a decent beat of analysts’ operating income estimates.
As expected, the stock is down 12.7% since the results and currently trades at $166.66.
Read our full analysis of KLA Corporation’s results here.
Nova (NASDAQ:NVMI)
Headquartered in Israel, Nova (NASDAQ:NVMI) is a provider of quality control systems used in semiconductor manufacturing.
Nova reported revenues of $255 million, up 15.9% year on year. This number surpassed analysts’ expectations by 1.6%. Overall, it was a very strong quarter as it also put up a significant improvement in its inventory levels and an impressive beat of analysts’ operating income estimates.
The stock is down 19.9% since reporting and currently trades at $322.22.
Read our full, actionable report on Nova here, it’s free.
Photronics (NASDAQ:PLAB)
Sporting a global footprint of facilities, Photronics (NASDAQ:PLAB) is a manufacturer of photomasks, templates used to transfer patterns onto semiconductor wafers.
Photronics reported revenues of $216 million, up 2.7% year on year. This result topped analysts’ expectations by 3.5%. It was an exceptional quarter as it also produced a beat of analysts’ EPS estimates and an impressive beat of analysts’ operating income estimates.
Photronics had the slowest revenue growth in the group. The stock is down 6.5% since reporting and currently trades at $27.40.
Read our full, actionable report on Photronics here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.